In 2026 the high-bandwidth memory (HBM) market sits at a strategic crossroads. Driven by generative AI, large language models, high-performance computing (HPC), and advanced graphics, demand for stacked memory with ultra-high throughput continues to surge. This post maps the 2026 HBM capacity expansions from the three dominant players—SK Hynix, Samsung, and Micron—examines their strategies, regional footprints, technology choices, and the implications for customers, OEMs, and the supply chain.
Why HBM matters in 2026
HBM remains the preferred memory for applications where memory bandwidth and energy efficiency matter more than cost per bit alone. Key drivers include:
- AI training and inference clusters that require massive data movement between processors and memory.
- GPU and accelerator designs prioritizing on-package memory for latency and power efficiency.
- Data center and HPC workloads where density, thermal characteristics, and interconnect advantages of HBM deliver performance per watt benefits.
By 2026, HBM architectures have matured across several generations—HBM2E, HBM3, and incremental HBM3e refinements. Each node targets higher per-die capacity, faster I/O, and lower power per bit. Production capacity and supply chain agility therefore determine who can meet customers' ramp schedules for next-generation accelerators and systems.
Overview of the 2026 capacity map
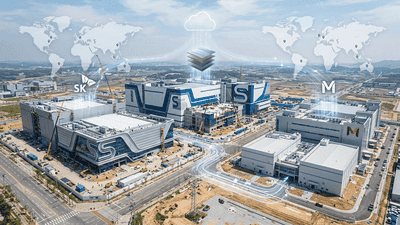
This section presents a consolidated view of HBM wafer and finished-module capacity across SK Hynix, Samsung, and Micron in 2026. The map focuses on:
- Major fabrication and packaging locations
- Relative capacity scale and recent expansion projects
- Technology mix by company (HBM2E / HBM3 / HBM3e)
SK Hynix
SK Hynix has been the most aggressive in the HBM segment, translating early investments into large-scale supply advantages. Their 2026 capacity profile highlights:
- Primary wafer fabs in South Korea (Icheon and Cheongju areas) focused on HBM3 and HBM3e die production.
- Significant packaging and testing capacity close to fabs, reducing logistics and lead time for memory stacks and interposers.
- Partnerships with OSATs for specialized fan-out and TSV processes to support higher die counts and larger capacities per stack.
- Targeting both HBM3 for mainstream AI accelerators and HBM3e for top-tier, high-bandwidth applications.
In 2026 SK Hynix continues to push volume on 10 nm-class DRAM processes optimized for stackable die geometries. Recent expansions prioritize yield learning for high-die-count stacks and expanding the throughput of test-and-bin lines dedicated to HBM formats.
Samsung
Samsung leverages its integration across advanced logic and memory manufacturing to compete on both process maturity and supply chain breadth. Key points for 2026:
- Large-scale DRAM fabs in Hwaseong and Pyeongtaek remain core for wafer output, with investments in HBM3 production lines.
- Heavy investment in packaging technologies—particularly silicon interposer and fan-out wafer-level packaging—to offer differentiated HBM modules with advanced signal integrity.
- Capacity expansions emphasize flexibility: Samsung can allocate lines between HBM2E, HBM3, and premium HBM3e depending on customer mix.
- Focus on co-optimized solutions for Samsung’s in-house GPU and accelerator customers while also selling to third parties.
Samsung’s geographic footprint and advanced packaging allow it to balance between high-volume commodity HBM and premium, performance-tuned modules. In 2026, it continues to convert some DRAM capacity to HBM production where margins and demand justify it.
Micron
Micron entered the HBM market later than the Korean players but has focused on targeted capacity and strategic partnerships. 2026 highlights:
- Principal HBM wafer production in the United States and key fabs in Asia configured for HBM3 and HBM3e die output.
- Outsourced packaging partnerships to accelerate time-to-volume while Micron ramps internal packaging capability.
- A product strategy oriented toward specific enterprise and hyperscaler customers, rather than broad-based commodity offerings.
- Selective expansion where long-term supply agreements justify capital intensity—Micron tends to scale capacity in measured phases rather than all-in rapid expansion.
Micron’s strengths in process control and differentiated memory IP help it win design-in deals for specialized accelerators. However, its overall HBM wafer-equivalent capacity in 2026 remains smaller than SK Hynix and Samsung, influencing how it negotiates customer commitments and pricing.
Regional capacity and supply-security considerations
HBM supply hinges on tight coupling between wafer fabs, advanced packaging, and OSATs. Geographic distribution matters because packaging capacity, test infrastructure, and logistics heavily affect lead times and risk.
- South Korea: The epicenter for SK Hynix and Samsung HBM capacity, with integrated fabs and packaging enabling short cycle times and responsiveness.
- United States: Strategic for Micron and for customers requiring onshore supply. U.S. capacity often targets hyperscalers and defense/HPC segments with strict procurement requirements.
- China and Taiwan: Important for OSAT and assembly capacity, though geopolitical and export-control dynamics can complicate flows for cutting-edge HBM products.
- Southeast Asia: Increasingly significant for test-and-pack operations, offering cost-efficient capacity and redundancy.
In 2026, a recurring theme is dual-sourcing and regional diversification. Large customers often require multiple qualified suppliers across different regions to manage geopolitical risk and ensure continuity during localized disruptions.
Technology choices and product mix
Not all HBM is created equal. Differences in die node, TSV density, interposer quality, and thermal characteristics create tiers of HBM products:
- HBM2E: Mature, higher-volume, used in applications where cost-performance balance is critical.
- HBM3: The mainstream standard for many AI accelerators in 2026, with higher bandwidth and density than HBM2E.
- HBM3e: The premium tier, pushing signaling rates and per-stack capacity, targeted at top-end training clusters and specialized HPC systems.
SK Hynix and Samsung both produce across these tiers, with SK Hynix often taking a leadership stance in HBM3e volume, while Samsung emphasizes flexible mixes and premium interposer-integrated modules. Micron focuses on selective HBM3/HBM3e production where customer commitments exist.
Capacity numbers: a comparative snapshot
While exact wafer-equivalent numbers fluctuate with internal allocations and confidential customer commitments, the 2026 landscape can be summarized qualitatively:
- SK Hynix: Largest global HBM capacity by wafer-equivalent and finished-module throughput, driven by large Korean fabs and integrated packaging.
- Samsung: Comparable wafer output, with capacity balanced between high-volume and premium packaging—overall capacity close to SK Hynix when packaging is included.
- Micron: Smaller total HBM capacity but strategically deployed for guaranteed supply to specific enterprise and hyperscaler customers.
Important caveat: capacity measured in wafer-equivalent terms differs from finished-module capacity because advanced packaging yields, reticle usage, and stack counts per module significantly affect final HBM units produced. Hence two companies with similar wafer output may yield different numbers of finished HBM stacks depending on die yields and packaging efficiencies.
Supply-demand dynamics and pricing pressure
2026 sees intense demand from AI and HPC but also rising supply as fabs and packaging lines ramp. This creates a nuanced pricing environment:
- Short-term spikes occur around new accelerator launches requiring HBM3e, giving suppliers leverage for premium pricing.
- Longer-term pricing pressure exists as SK Hynix and Samsung scale volumes; Micron’s selective strategy helps sustain margins where it has guaranteed demand.
- Customers are negotiating multi-year supply contracts, capacity reservations, and co-investments to secure prioritized access during critical ramps.
OEMs and large hyperscalers often accept higher unit prices for guaranteed delivery and roadmap alignment. At the same time, commoditization in lower-tier HBM segments (older HBM2E parts) exerts downward pressure on average selling prices.
Packaging bottlenecks and OSAT roles
HBM production is packaging-heavy: TSV formation, hybrid bonding, precision stacking, interposer fabrication, and thermal solutions are non-trivial. Packaging constraints remain a primary bottleneck in 2026.
- OSAT capacity has expanded, but high-end hybrid bonding and silicon interposer capacity are still limiting factors for the highest-stack-count HBM3e modules.
- Suppliers with in-house packaging (SK Hynix, Samsung) enjoy faster integration and yield learning loops, reducing time-to-volume for new formats.
- Micron’s reliance on partners enables quick scale in assembly but requires careful quality control to match the yield targets of vertically integrated rivals.
For customers, packaging constraints translate to lead-time variability. Engaging with multiple suppliers and committing to long-term purchase agreements are common tactics to mitigate scheduling risk.
Implications for customers and OEMs
For system designers, procurement teams, and hyperscalers the 2026 HBM capacity race implies several practical takeaways:
- Plan with flexibility: design systems that can support alternative HBM suppliers and slightly different module pinouts where feasible.
- Secure supply via contracts: multi-year agreements, capacity reservations, and co-investment in packaging capacity remain useful tools.
- Prioritize qualification early: qualifying multiple HBM sources during prototype phases shortens transition time once production volumes are needed.
- Watch thermal and power envelopes: HBM3e pushes both bandwidth and thermal demand—system-level cooling and power delivery must be considered in procurement timelines.
Geopolitics, export controls, and strategic risk
Geopolitical considerations continue to shape where and how HBM capacity is built and sold. Export controls on advanced node tools, silicon interposer technologies, and packaging equipment can influence lead times and supplier allocations.
As a result:
- Hyperscalers and defense-related customers emphasize onshore or allied-country sourcing for critical components.
- Suppliers hedge risk via multi-region capacity and cross-licensing of key process steps where possible.
- Capacity expansions announced with governmental incentives often come with procurement preferences or domestic content requirements that complicate global supply planning.
What to watch in the rest of 2026
Several developments will determine how the capacity map evolves through the year:
- Yield improvements on HBM3e hybrid bonding and TSV processes—higher yields unlock meaningful increases in finished-module output without additional wafer capacity.
- Announcements of new OSAT partnerships or in-house packaging facilities—these materially change packaging bottlenecks.
- Large design wins by new accelerator startups or cloud providers—customer commitments can tilt allocation toward one supplier.
- Policy and export-control updates—restrictions or incentives could accelerate regional reshoring or further diversify supply chains.
Short strategic recommendations
For different players in the ecosystem, the following concise actions are practical:
- Hyperscalers/OEMs: Lock in multi-year supply agreements and qualify at least two HBM suppliers before mass production.
- Chip designers: Optimize memory interface flexibility to reduce supplier lock-in and support alternate HBM pinouts or speeds.
- Suppliers: Invest in packaging yield learning and hybrid-bond capacity; maintain close OEM partnerships to secure premium allocations.
- Policymakers: Support secure, diversified advanced packaging ecosystems to reduce systemic risk for critical compute infrastructure.
Conclusion
The 2026 HBM capacity race is less a single sprint and more an ongoing contest of integrated manufacturing, packaging expertise, and commercial strategy. SK Hynix and Samsung lead in sheer scale and vertical integration, enabling faster volume for HBM3 and HBM3e. Micron, while smaller in total HBM output, plays a focused role with tightly negotiated customer partnerships and selective scaling. Packaging capacity and yield remain the true limiter for finished HBM stacks—so investments in advanced packaging, OSAT partnerships, and yield engineering will determine who actually reaches customers on time.
For buyers and system designers, the map of available capacity in 2026 means balancing price with security of supply. Strategic procurement, early qualification, and design flexibility are essential to navigate a market where demand can spike with the next major accelerator launch, and where regional considerations and policy moves can shift the capacity map with little notice.